
Bright: Loans & Credit Builder
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
Bright: Loans & Credit Builder - Screenshots
Pros
- Simple application process with clear eligibility information.
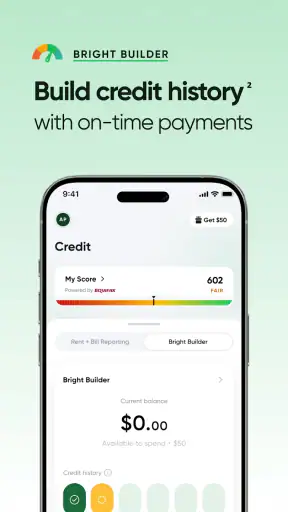
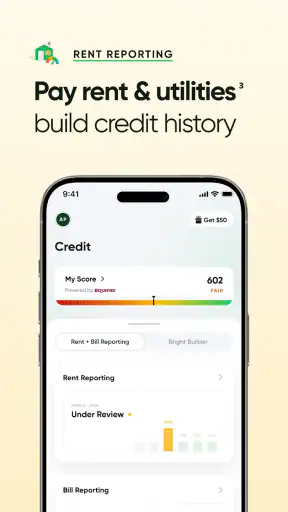
- Credit-building tools can help establish a payment history over time.
- Loan options may be useful for borrowers with limited credit.
- Repayment details are presented before accepting an offer.
- Digital account management makes tracking payments convenient.
Cons
- Approval
- rates
- and loan terms vary by applicant and are not guaranteed.
- Interest and fees may make borrowing expensive for some users.
- Late payments could further damage your credit score.
- Some features may require identity and income verification.
- Availability and loan options can depend on your location.
Bright: Loans & Credit Builder - Description
- App Name
- Bright: Loans & Credit Builder
- Package Name
- com.brightcapital.app
- Developer
- Bright Money
- Category
- Finance
- Last Updated
- Aug 31, 2020
- Version
- 1.61.1
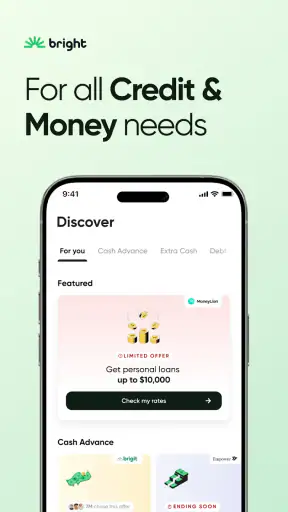
When I first opened Bright: Loans & Credit Builder, I understood its appeal quickly: it is a finance app aimed at people who want a clearer route toward building credit, finding borrowing options, or exploring credit cards without jumping between several unrelated services. Bright Money develops the app, and its focus is less about everyday banking and more about helping users think through credit decisions.
That focus makes it especially interesting for someone using credit for the first time. The app is free to install, available to users rated Everyone, and has built a sizeable audience, with more than a million installs and an average score of 4.6 from roughly 165 thousand ratings. Those figures suggest that many people find the general idea useful, but they should not be mistaken for a promise that every user will receive the same loan, card, or credit-building result.
My overall impression is that Bright works best as a guided starting point. It can help you organize your next credit-related decision, but it is not a magic shortcut to a higher score or guaranteed approval. The most important part of using it well is entering the process with realistic expectations and reading every offer carefully before accepting anything.
What to expect before you begin
The app presents itself as an AI loan assistant with credit-building and borrowing goals. In practical terms, I would approach it as a decision-support tool rather than a replacement for a bank, a personal finance adviser, or a full budgeting application. Its value is concentrated around credit: understanding possible paths, reviewing available choices, and taking a more deliberate next step.
A first-time user may expect to open Bright and immediately see a loan or a credit card. That is not the mindset I recommend. Financial products depend on personal circumstances, eligibility, and the information used during the application process. The useful result may instead be a better understanding of what kind of credit option fits your situation, what you need to review, and whether applying now makes sense.
The app comes from Bright Money, and its store presence lists a current version of 1.61.1 for devices running Android 8.0 or later. That makes it accessible to many older Android phones, although I would still keep the operating system updated where possible. Finance apps deserve extra care because an outdated phone can make account security and general device maintenance more difficult.
Bright is not the right choice for every financial task. If your main goal is tracking groceries, splitting bills, monitoring investments, or replacing a traditional checking account, a dedicated app in one of those areas will probably serve you better. Bright makes more sense when your immediate question is, “What should I do next with my credit?”
Set a clear goal before entering information
Before installing, I would decide which of three broad goals matters most to me: building credit, exploring loans, or looking at credit card possibilities. These goals overlap, but they are not identical. Someone trying to establish a credit history needs a different approach from someone comparing borrowing for an urgent expense.
This small preparation step prevents a common mistake: accepting the first attractive-looking option simply because it appears inside a finance app. Write down the amount you can comfortably repay, the reason you need credit, and the monthly payment that would remain manageable even if your budget becomes tighter. Bright can help with the search process, but it cannot make an unaffordable payment safe.
I would also gather the basic personal and financial information normally needed for a credit-related application before beginning. Having details ready makes the setup less frustrating and gives you time to notice inconsistencies in your information. A misspelled name, outdated address, or incorrect income detail can create confusion later, so accuracy matters more than speed.
Getting through the first setup without rushing
The first setup should be treated as a review of your financial profile, not as a formality to click through. Read each screen, check why information is being requested, and pause whenever a question is unclear. In a finance app, the fastest route is not always the safest route.
I would start by checking that the app is the genuine Bright Money product and that the developer name matches Bright Money. I would then use a strong device passcode and avoid beginning the process on a public or shared phone. These are simple habits, but they are more important here than they would be in a casual game or entertainment app.
During setup, keep your personal answers consistent with your actual situation. Do not adjust income, employment, or housing details merely because you think a different answer might improve your result. An application built on inaccurate information can create more trouble than it solves, and it makes any later recommendation less meaningful.
One useful habit is to take notes outside the app while you work. Record the purpose you selected, the amount you are considering, and any repayment details that appear. This gives you something to compare later if you look at an offer from a bank or another lender. It also helps separate Bright’s guidance from the final terms of a product.
What the setup can and cannot tell you
Bright may make credit-related choices feel more approachable, but a guided screen is not the same as an approval. A recommendation or available option should be read as an invitation to inspect terms, not as evidence that the product is automatically affordable or beneficial for your credit history.
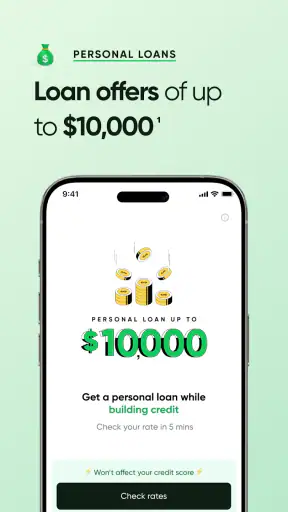
I would pay particular attention to the difference between building credit and borrowing money. A credit-building route may be more appropriate when the main objective is establishing responsible payment history. A loan may be appropriate for a specific, necessary expense, but it also adds a repayment obligation. A credit card can offer flexibility, yet carrying a balance can become expensive if it is not managed carefully.
This is one of the app’s most important trade-offs. Bringing these possibilities into one place is convenient, especially for a beginner, but convenience can make distinct financial products look more similar than they really are. I would always compare the total cost, payment schedule, fees, and consequences of missed payments before moving forward.
Privacy and attention are part of the setup
Financial applications require a higher level of attention than ordinary utility apps. I would read the relevant disclosures and permissions rather than approving everything automatically. If a screen asks me to connect information or authorize an action, I want to understand what that action is for before continuing.
I would also avoid using Bright while distracted. A five-minute setup completed carefully is better than a rushed session during a commute. If you are uncomfortable with a question, stop and investigate it through the app’s own explanations or official support route before submitting anything. That pause is not wasted time; it is part of making a responsible credit decision.
Reaching the first meaningful success
For a new user, the first meaningful success should not be “I received a loan.” A better first win is leaving the app with a clear, affordable next step and a full understanding of what it involves. That might mean identifying a credit-building direction, narrowing down a borrowing need, or deciding not to apply yet.
My suggested workflow is simple. First, choose the goal that best describes your situation. Next, review the information Bright uses to shape its guidance. Then, inspect any option slowly and write down its important terms. Finally, compare that option with at least one familiar alternative, such as your existing bank or a credit union you already trust.
This comparison is where Bright can be more useful than searching randomly online. Instead of opening many pages with different terminology, you can use the app to organize your thinking around your own objective. However, I would not let the convenience of a single interface stop me from checking the original provider’s terms.
A realistic example would be a person who has recently moved to the United States, has limited credit history, and wants to improve their profile before renting a better apartment. They open Bright looking for a credit card, but their real need is predictable payment behavior and a manageable monthly commitment. Rather than choosing the largest available amount, they can use the app as a prompt to consider whether a credit-building option fits their budget and whether they can make every payment on time.
Another example is someone facing an unexpected car repair. Bright may help them explore borrowing possibilities, but the successful decision could be realizing that the repayment would strain their next several paychecks. In that case, closing the application and seeking a less costly alternative is a positive outcome, even if it feels less exciting than accepting an offer.
Use the app as a comparison checkpoint
One non-obvious advantage of a credit-focused app is that it can serve as a checkpoint between anxiety and action. When money is tight, people often apply impulsively. I found the most sensible use of Bright to be slowing that impulse down: define the need, inspect the option, and ask whether the payment still works after rent, food, transport, and existing bills.
Keep a personal record of the products you consider and the dates you review them. This is useful because it stops your financial decisions from becoming a series of disconnected screens. If you later speak with a bank or counselor, you can explain what you were trying to accomplish rather than simply saying that an app showed you an offer.
Do not assume that viewing an option means you should pursue it. The app’s role is helpful when it improves your judgment. It becomes less helpful if you treat every recommendation as a target to unlock. For credit-building, consistency and affordability matter more than chasing the biggest possible line or loan amount.
Where first-time users may get confused
The biggest source of confusion is the phrase “build your credit.” Credit improvement is usually the result of repeated financial behavior, not one installation or one application. Paying obligations on time, keeping borrowing manageable, and checking the terms of each product are more important than the excitement of finding an available offer.
Another confusing point is the difference between an estimated possibility and final product terms. An early screen may help you decide whether to continue, but the final conditions can depend on the provider’s review. I would never make a purchase, move, or emergency decision based only on an initial indication inside the app.
Users may also confuse a loan assistant with a budgeting tool. Bright can be relevant when deciding how to approach credit, but it does not replace a complete monthly spending plan. Before accepting any repayment obligation, I would use a separate budget method if necessary and include the new payment alongside existing bills.
There is also a psychological trap: seeing several credit choices in one place can create the feeling that more options are always better. They are not. A simple, affordable option that matches your goal is often better than a more flexible product with terms you do not fully understand.
When another option is better
If you already have a trusted bank and need a small, clearly defined service, contacting that bank directly may be simpler. Existing customers sometimes prefer the familiarity of their current provider, its support channels, and its established records. Bright is more valuable when you need help framing your next credit step rather than when you already know exactly which product you want.
If debt is already difficult to manage, I would be cautious about using any borrowing-focused pathway. A nonprofit credit counselor, a qualified financial professional, or a direct conversation with existing creditors may be more appropriate than searching for another loan. Bright can help someone explore choices, but it should not be used to hide a repayment problem under a new obligation.
Likewise, users who dislike sharing financial information digitally or who prefer face-to-face explanations may feel more comfortable with a local institution. The app’s convenience will not outweigh that concern if you are uneasy throughout the process. Confidence and understanding are essential when the subject is credit.
The next step after your first session
Once I had finished the initial exploration, I would not immediately return to browse every available possibility. I would choose one practical next step: review terms with the provider, prepare a repayment plan, improve the accuracy of my information, or wait until my finances are more stable.
If you decide to continue, set a reminder to check your payment plan and keep your records organized. A credit-building strategy only works when it fits your routine. Automatic reminders, a dedicated budget category, or a simple calendar note can reduce the chance that a payment is forgotten.
If you decide not to continue, that is also a useful result. Close the session, keep your notes, and revisit the question when your income, expenses, or credit goal changes. There is no benefit in forcing a decision simply because the app made the process easy to start.
Bright is free, which lowers the barrier to trying its credit-focused guidance, but free access should not be confused with free borrowing. The real cost of any loan or credit product comes from its terms, not from the price of downloading the app. That distinction is worth repeating because it is the easiest detail for a first-time user to overlook.
After using it, I see Bright Money’s app as a practical entry point for people who feel lost around credit and want a more structured way to explore loans, credit cards, or credit-building possibilities. Its strongest quality is the way it puts those questions into a single guided experience. Its main weakness is that the same simplicity may encourage users to move too quickly or treat a possible offer as a recommendation they must accept.
With the current version, 1.61.1, and support for Android 8.0 or newer, the app is easy for many Android users to try. I would recommend it to a beginner who is willing to read carefully, compare alternatives, and treat every repayment decision seriously. I would skip it if I wanted a complete budgeting system, if I already knew exactly which bank product I wanted, or if I was looking for a solution to an existing debt crisis.
My advice is to judge success by clarity, not by approval. If Bright helps you understand your goal, recognize the cost of a decision, and choose an affordable next step, it has done something genuinely useful. Used that way, it can be a reassuring first guide into credit rather than another app asking you to act before you are ready.
FAQ
What is Bright: Loans & Credit Builder, and how does it work?
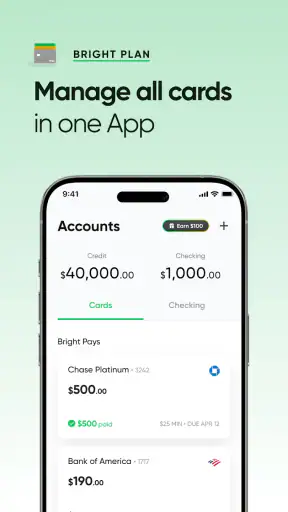
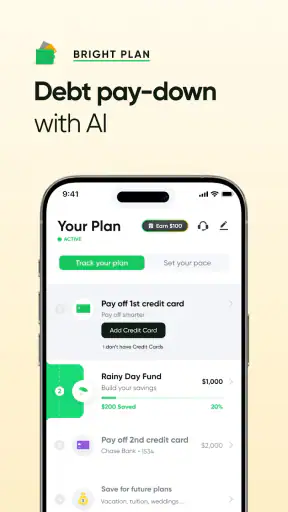
Bright is a personal finance app designed to help users manage debt, build credit, and organize repayments. After connecting eligible financial accounts, the app may analyze your finances and suggest a repayment strategy. Depending on your profile and location, Bright can provide access to credit-building tools or loan-related services. Availability, eligibility, and exact features may vary, so review the terms carefully before enrolling.
Can Bright guarantee that my credit score will increase?
No credit-building app can guarantee a specific improvement in your credit score. Bright may support healthier financial habits by helping you make payments on time, manage debt, or use certain credit-related products responsibly. However, results depend on your existing credit history, account activity, payment behavior, and information reported to credit bureaus. Late payments, new applications, or other financial actions could still affect your score negatively.
Does Bright charge fees, interest, or subscription costs?
Bright may involve membership charges, service fees, loan costs, or interest depending on the product and offer available to you. The amount and billing schedule should be shown during registration or before accepting an agreement. Read the annual percentage rate, repayment amount, cancellation policy, and any automatic renewal terms carefully. Do not assume that credit-building assistance or loan access is free simply because the app can be downloaded without charge.
Is my financial information safe when I connect my accounts to Bright?
Bright requires financial information to provide features such as account analysis, repayment planning, or eligibility checks. Before connecting an account, review the app’s privacy policy and understand what data may be collected, how it is used, and whether it is shared with service providers or financial partners. Use the official app listing, protect your login credentials, enable available security features, and disconnect accounts if you stop using the service.
Who is eligible to use Bright, and is it available everywhere?
Bright’s availability and eligibility requirements depend on factors such as your country or state, age, identity verification, income, banking history, and credit profile. Some services may only be offered to users with compatible bank accounts or specific financial circumstances. Approval is not guaranteed, and downloading the app does not mean you qualify for every feature. Check the current requirements and product disclosures in the app before submitting personal information.


